ARTICLES / BLOG
Conscious Finances
In everyday life, we often manage our finances based on instinct and intuition. We encounter financial advertisements, recommendations from advisers and offers through various channels. There are many risks around us, and a great deal of noise. Marketing uses a range of techniques to stimulate our desire to buy and own things, supporting the sales objectives of service providers.
One of the foundations of responsible financial behavior is to reduce impulse purchases and, whenever possible, base our decisions on facts and data rather than momentary desires or fears. To do this, however, we must first understand ourselves: what do we want to achieve, what resources do we have, how much time is available to us and what risks are we willing to take?
The income and wealth we create, along with the standard of living they enable, often reflect the time, energy and added value we have generated throughout our lives. Of course, there are exceptions, such as inheritance or family wealth, but these too represent value created in the past.
Money is therefore more than a collection of numbers in a bank account. Behind it lie work, time, decisions and opportunities. That is precisely why we should handle it thoughtfully.
Finance is an interesting subject: not everyone has money, but everyone has financial matters to deal with. A lack of knowledge about how the economy works and the rules of capitalism does not exempt anyone from the consequences of their decisions. At the same time, money is “only” a tool, not a goal in itself.
I firmly believe that people must remain at the center of financial planning. We should not look for goals to match financial products; instead, we need to find the right tools and services to achieve our own goals.
To do this, we must first distinguish between our goals and our desires. We experience countless desires every day, and they often disappear just as quickly as they arise. A genuine goal, by contrast, is specific, realistic, achievable, measurable, and both time-bound. The more precisely we formulate it, the easier it becomes to plan the path towards achieving it.
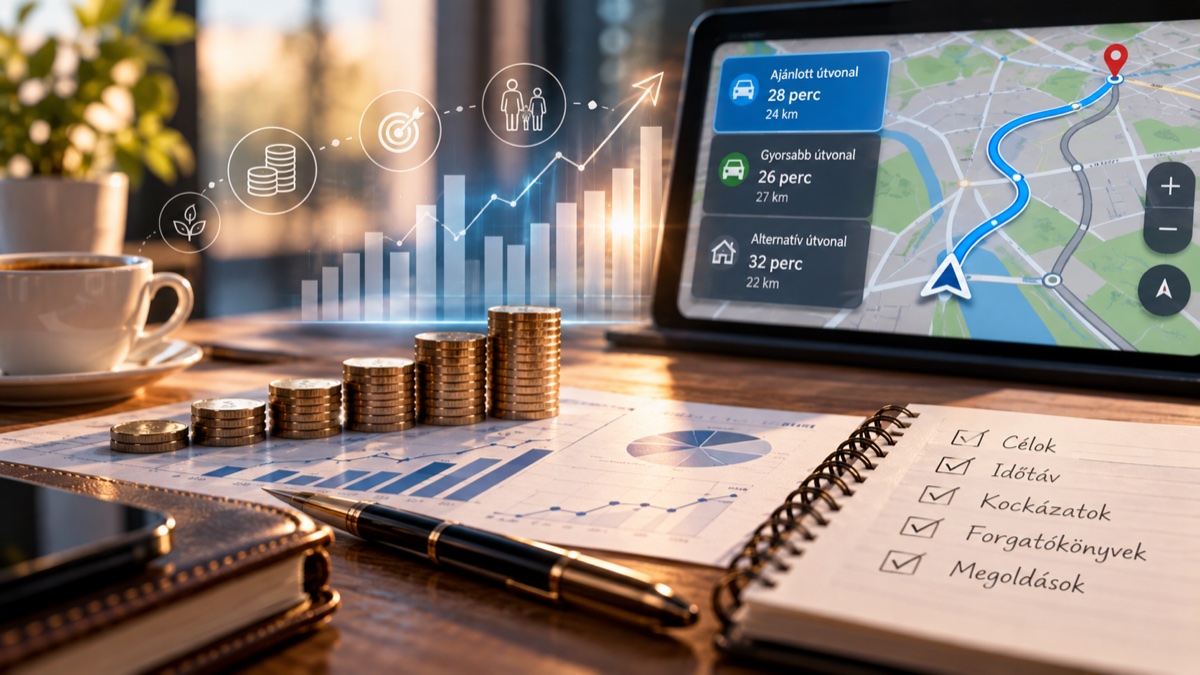
Financial planning is similar to using a car navigation system. When we set off on a journey, we first enter our destination. Based on the information available, the navigation system may suggest several routes, allowing us to choose according to travel time, distance or other considerations.
Circumstances may change during the journey. Traffic jams, roadworks or accidents may force us to change our original route. Yet we do not lose sight of our destination, nor do we necessarily need to return to our starting point. We simply recalculate the route. This is how I envision effective financial planning.
We should define our goals, assess our resources and develop several possible scenarios. We need to consider which circumstances might help or hinder our plans. Where necessary, we should seek professional support.
The world is constantly changing, so our financial plans cannot remain fixed. Flexibility, however, is not the same as having no direction. We are in a much better position when we need to adjust a carefully considered plan than when unexpected circumstances force us into a situation for which we are unprepared.
“Man proposes, God disposes,” as the saying goes. We cannot always influence circumstances, but we can influence how well we prepare for them.
Decisions made in the past affect our present circumstances, while the decisions we make today shape our future. Moreover, not making a decision is itself a decision. When we procrastinate, we often unknowingly give up certain opportunities or postpone their realization.
This is particularly important when it comes to long-term goals. Starting to save at the right time, making a well-considered financial decision or recognizing a risk early can make a significant difference to our quality of life years later.
Preserving the assets we already have and increasing their value where possible is our own responsibility. We do not need to understand every financial product or economic relationship in detail, but we should be aware of our goals, our resources and the consequences of our decisions.
Responsible financial behavior is not simply about saving money or building wealth. More importantly, it is about ensuring that our financial decisions are aligned with our life goals, values and circumstances.
Money is a tool that can help make our lives more secure, predictable and full of opportunities. Planning helps us do more than simply drift with circumstances: it enables us to shape our future consciously.
Would you like to review your own financial situation and goals as a whole?
During the initial needs-assessment consultation, we review your current situation and possible next steps.